Consulting · 12 Min Read
August 2026
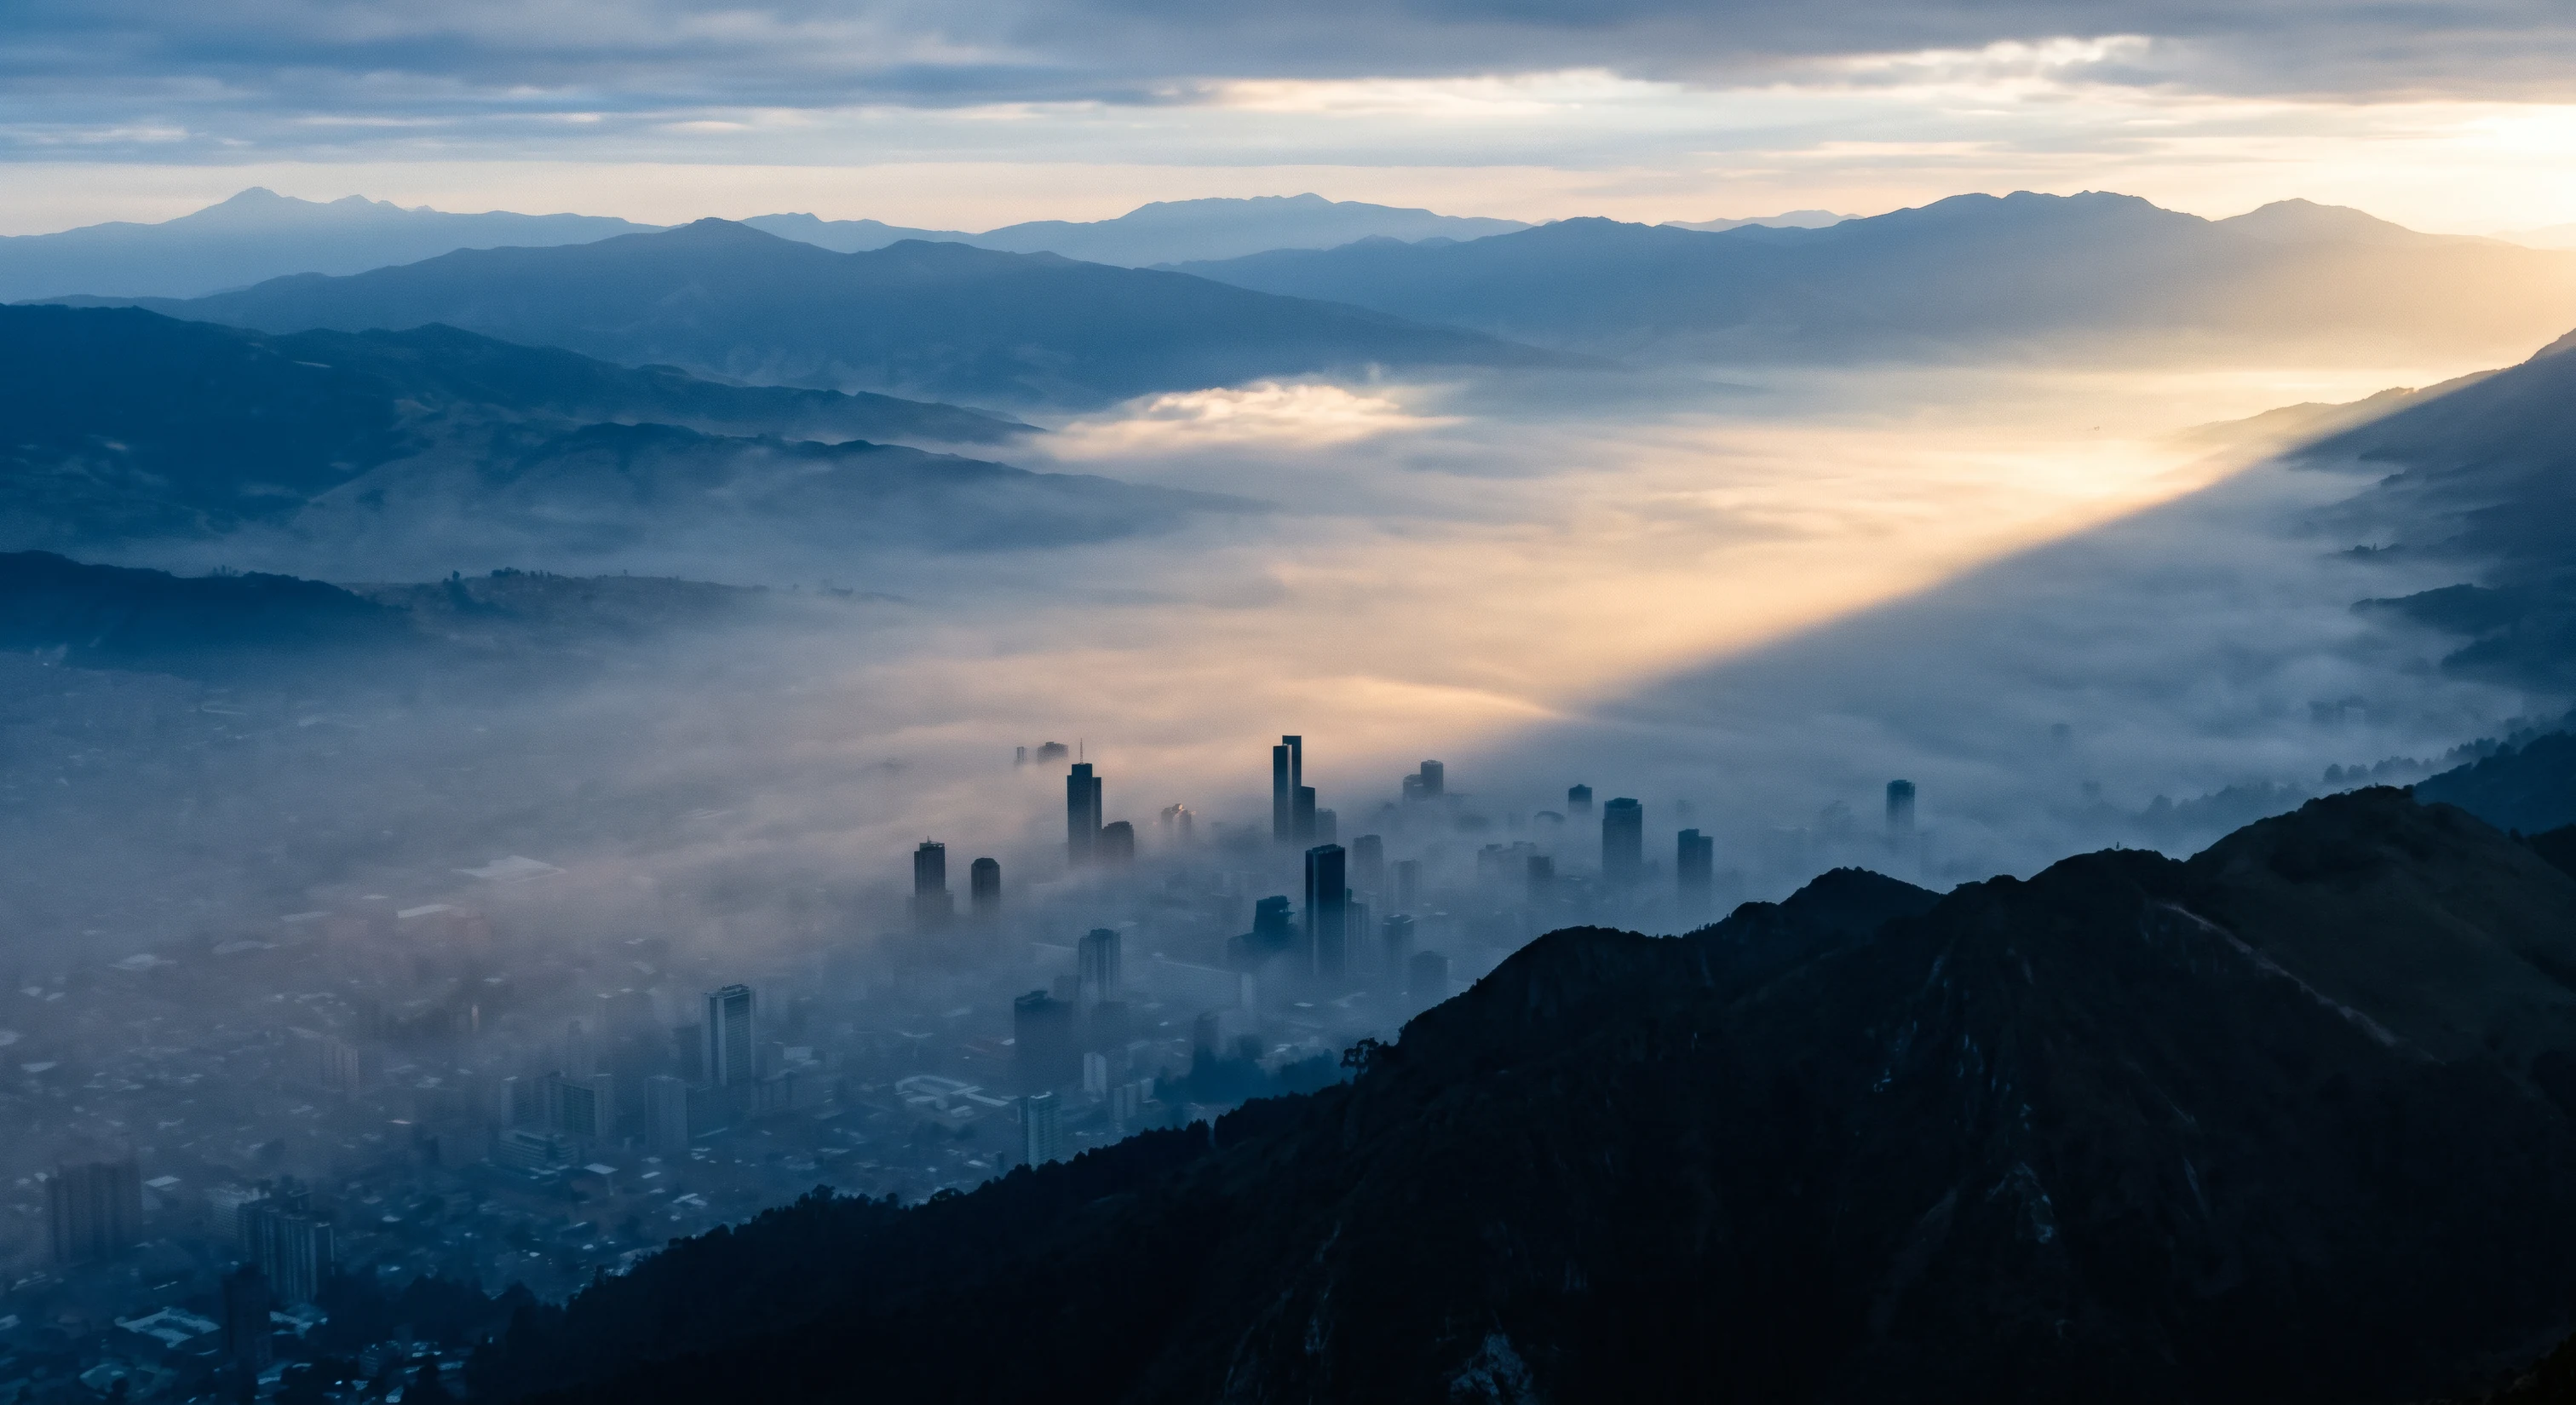
Bogotá is routinely described as Latin America's emerging financial gateway. The description is not wrong, but it is incomplete in a way that matters to anyone deciding where to place capital. The structural advantages are real and durable. The investment flows, measured honestly, moved in the opposite direction through 2025 and the first half of 2026. Understanding both is what separates a considered entry from an expensive one.
The Transformation Story
Bogota's financial renaissance did not happen by accident. It is the result of deliberate policy decisions spanning over two decades: investment in infrastructure, modernization of regulatory frameworks, and strategic positioning within global trade networks. The city now hosts the regional headquarters of over 1,700 multinational corporations, more than any other Latin American capital.
The Colombian government's commitment to economic liberalization, combined with a young, highly educated workforce, has created an ecosystem where international business can operate with confidence. Bilateral investment treaties with over 16 countries provide legal certainty, while free trade agreements with the European Union and the United States open doors to preferential market access.
Free Trade Zones and Tax Incentives
Colombia's free trade zone regime offers compelling advantages for international investors. Companies operating within designated zones benefit from a reduced corporate income tax rate, exemption from customs duties on imports, and streamlined regulatory procedures. These zones are not confined to manufacturing — services, technology, and healthcare sectors have all established significant presence.
Beyond free trade zones, Colombia offers targeted incentives for specific industries. The orange economy legislation promotes creative industries, while renewable energy investments benefit from accelerated depreciation and VAT exemptions. For advisory firms guiding international clients, understanding the interplay between these incentive regimes and home-country tax obligations is where true value is created.
The Fintech Revolution
Bogota's fintech ecosystem has grown exponentially, positioning Colombia as the third-largest fintech market in Latin America. Digital payment platforms, neobanks, and blockchain-based solutions are transforming how Colombians interact with financial services, reaching previously unbanked populations across the country.
This digital transformation creates opportunities not just for technology companies but for the entire advisory ecosystem. Regulatory frameworks for digital assets, open banking regulations, and data privacy compliance all require sophisticated guidance that bridges local knowledge with international best practices.
"Bogota does not aspire to become the next global financial center — it is quietly and deliberately becoming one."
Infrastructure and Connectivity
The expansion of El Dorado International Airport, South America's third-busiest cargo hub, alongside investments in the Bogota Metro and regional highway networks, signals the city's ambition to match its financial sophistication with world-class physical infrastructure. Direct flights to major European and North American cities reduce the friction of international business operations.
Digital infrastructure has kept pace. Colombia ranks among the top Latin American countries for internet penetration and mobile connectivity, providing the backbone for an increasingly digital economy. Co-working spaces, innovation hubs, and technology parks dot the city's northern corridor, creating an environment where startups and established enterprises coexist and collaborate.
The Gateway Advantage
Bogota's geographic position — equidistant from Mexico City and Buenos Aires, with time zone alignment to North American business hours — makes it the natural base for regional operations. Companies seeking to serve the broader Latin American market increasingly choose Bogota not despite its complexity, but because navigating that complexity builds the operational muscle needed to succeed across the region.
At Castillo & Co, our Bogota office stands at the intersection of local expertise and global perspective. We have witnessed the city's transformation firsthand and have helped our clients — from European multinationals to Colombian entrepreneurs expanding abroad — capture the opportunities that this renaissance presents. The story of Bogota's financial rise is still being written, and the most compelling chapters lie ahead.
The Numbers Behind the Narrative
Foreign direct investment into Colombia reached USD 11,469 million in 2025 — a decline of 16.1% from the previous year and roughly a third below the 2022 peak. In the same period Colombia fell from third to fifth place among recipients in Latin America and the Caribbean, behind Brazil, Mexico, Chile and Peru, while the region as a whole grew 1.7%.
The trend did not reverse in 2026. Measured through the exchange balance, investment flows in the first half of the year fell 12.3% against the same period of 2025, with six consecutive months of annual decline. A widely reported first-quarter figure showing 34% growth comes from a different series — the balance of payments — and is not sustained by the monthly data through June.
Any assessment of Bogotá that does not engage with these figures is a brochure rather than an analysis.
What the Composition Actually Says
The headline decline is not the most instructive part. The composition is.
In the first half of 2026, investment into oil and mining fell 5.4%, to USD 3,439 million. Everything else — manufacturing, commerce, infrastructure, services, agribusiness, technology — fell 32%, to USD 874 million. Close to 80% of foreign investment concentrated in extractive sectors.
Colombia therefore became more dependent on extractive capital during a period in which policy explicitly sought the opposite. For a manufacturer or a services group, that statistic carries an unexpected implication: the field has thinned considerably. Competition for quality non-extractive assets, for skilled local partners, and for well-located industrial space is weaker than it has been in years.
Whether that reads as risk or as opportunity depends on the time horizon. Capital that entered Colombia in the difficult years of the early 2000s compounded considerably.
The Case That Survives the Data
Free trade zone treatment remains materially advantageous.
The 20% corporate rate applicable to qualifying free trade zone users, against a 35% general rate, is among the more competitive regimes in the region — subject to the annual compliance benchmarks that determine continued eligibility. That structure was not affected by the emergency decree that the Constitutional Court annulled in April 2026, and no announced reform has proposed dismantling it.
Geography is not a policy variable.
Bogotá sits within five hours of most major markets in the Americas, in a time zone that overlaps the full working day in both New York and São Paulo. For a regional treasury function, a shared services centre or a back office serving North American operations, that alignment is worth more than a tax point or two — and it does not change with an election.
The talent base is deep and comparatively affordable.
Colombia produces a substantial volume of accounting, engineering and technology graduates annually, with English proficiency concentrated in Bogotá and Medellín. Fully loaded cost per qualified professional remains well below equivalent roles in North America, and turnover in professional services is lower than in several competing regional hubs.
What Changes with the New Government
A new administration takes office on 7 August 2026 having announced an economic agenda oriented toward simplification: a reduction of the DIAN's remit to three principal taxes, elimination of the financial transactions levy and of the wealth tax, and a reversal of restrictions on hydrocarbon exploration.
None of this is law, and a mandate of less than one percentage point over a Congress the government does not control is a meaningful constraint on how much of it passes. The relevant discipline for anyone evaluating Colombia is the same one that applies to the investment data: distinguish what is confirmed from what is announced, and size the position accordingly.
Published by the editorial team at Castillo & Co. The views expressed reflect our firm's perspective on current market trends and should not be construed as investment advice.